








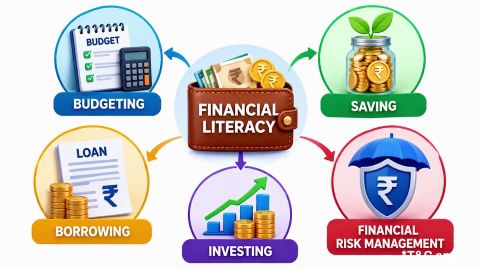
What is financial literacy
-
In summary
Financial decisions determine how money is allocated to meet current needs and future objectives. For individuals, they involve managing income, expenses, savings, investments and borrowing. For businesses, they influence investment plans, funding sources and profit distribution.
The three main corporate finance decisions are:
- Investment decisions: Choosing assets, projects or activities in which to deploy funds.
- Financing decisions: Determining how to raise the money required, such as through debt, equity or internal resources.
- Dividend decisions: Deciding how much profit to distribute to shareholders and how much to retain for future use.
Sound financial decisions consider affordability, risk, expected returns, liquidity, cash flow and the time available to achieve a goal. Individuals can begin by creating a budget and setting aside money for emergencies. Once immediate needs are covered, they can compare suitable savings and investment options according to their goals and risk tolerance.
What is a financial decision?
A financial decision is a choice about how money should be obtained, allocated, managed or used to achieve an objective. It may relate to everyday spending, saving for a future expense, taking a loan, investing in an asset or managing a company's capital.
For individuals, a financial decision could involve deciding how much of a monthly salary to save, whether to repay debt early or how to fund a planned purchase. For a business, it could involve investing in new equipment, raising funds to expand operations or determining how much profit to distribute to shareholders.
A financial decision should account for both immediate requirements and future consequences. For example, using all available savings for a purchase may leave insufficient money for emergencies. Similarly, a business taking on excessive debt may find it difficult to meet repayments if revenue falls.
The aim is not necessarily to choose the option with the highest potential return. It is to choose an option that fits the objective, available resources, time horizon and ability to bear risk.
What are the three main financial decisions in corporate finance?
-
Corporate finance generally groups key financial decisions into three categories: investment, financing and dividend decisions. These decisions are connected because a business must decide how to use funds, where to obtain them and what to do with the profits it generates:
1. Investment decisions
Investment decisions involve choosing how a business should allocate its funds. These decisions may relate to purchasing machinery, opening a new facility, developing a product, entering a market or investing in technology.
Before approving an investment, a business may assess:
- The expected cash flows and potential returns.
- The initial cost and ongoing expenses.
- The time required to recover the investment.
- The risks and uncertainties involved.
- Whether the project supports the business's objectives.
For example, a manufacturing company considering new machinery would compare the purchase cost with the expected benefits, including possible changes in production capacity, operating costs and revenue.
2. Financing decisions
Financing decisions determine how a business will obtain the funds required for its operations and investments. Common sources include equity, loans, bonds, retained earnings and other financing arrangements.
The choice depends on factors such as borrowing costs, repayment capacity, ownership considerations, cash flow and the intended use of funds.
For instance, a company expanding its operations may compare a business loan with issuing new shares. A loan involves interest and repayment obligations, whereas issuing shares can dilute the ownership percentage of existing shareholders.
3. Dividend decisions
Dividend decisions concern how much of a company's profit should be distributed to shareholders and how much should be retained in the business.
A company may retain more earnings when it needs funds for expansion, debt repayment or other investments. It may distribute a portion of its profits as dividends when this is consistent with its financial position, business plans and applicable requirements.
The decision involves balancing shareholder expectations with the company's future funding needs.
What are the different types of financing decisions?
-
Financing decisions can be classified according to where the funds come from, how long they are needed and the terms attached to them:
1. Equity financing
Equity financing involves raising capital by issuing shares or bringing in investors. The funds do not generally create scheduled loan repayments, but new share issues may reduce existing shareholders' ownership percentages.
This type of financing may be considered when a business needs capital for growth and wants to avoid additional debt repayments. However, investors may expect a return and may receive ownership or voting rights.
2. Debt financing
Debt financing involves borrowing money through loans, bonds, debentures or other debt instruments. The borrower must meet the repayment and interest obligations set out in the agreement.
Debt can allow existing owners to retain their ownership percentages, but it creates financial commitments. Before borrowing, a business needs to assess whether its expected cash flow can support repayments under different business conditions.
3. Short-term financing
Short-term financing is used to meet near-term funding needs, such as purchasing inventory, paying suppliers or managing temporary gaps between receipts and expenses.
Sources may include trade credit, working capital facilities and short-term loans. The business should consider the total cost, repayment schedule and the risk of needing to refinance the borrowing.
4. Long-term financing
Long-term financing supports projects or assets that are expected to provide benefits over an extended period. Examples include factory expansion, major equipment purchases and infrastructure development.
Sources may include long-term loans, bonds and equity capital. The funding period should broadly align with the expected use of the funds and the business's ability to repay or provide returns to investors.
5. Internal financing
Internal financing uses funds generated or retained within the business, such as retained earnings and accumulated reserves.
Using internal funds may reduce the need for external borrowing or new share issues. However, the business must also consider whether using those funds would leave insufficient working capital or reduce its ability to respond to unexpected expenses.
6. Hybrid financing
Hybrid financing combines characteristics of debt and equity. Convertible debentures are one example: they may begin as debt and convert into equity under specified terms.
Hybrid instruments can offer flexibility, but their terms may be more complex. Businesses should understand the repayment conditions, conversion features, ownership implications and costs before choosing this option.
What factors affect financial and financing decisions?
A sound financial decision requires more than comparing headline returns or interest rates. The following factors can influence the choice:
1. Risk
Risk refers to the possibility that the actual outcome will differ from what was expected. For businesses, this may include changes in sales, borrowing costs, market conditions or customer demand. For individuals, it may include income uncertainty, unexpected expenses or investment losses.
A business with volatile cash flows may need to be cautious about taking on fixed debt repayments. Similarly, an individual should consider their ability to absorb a loss before choosing a market-linked investment.
Risk assessment should reflect both the likelihood of an adverse outcome and the potential impact on the financial position.
2. Ownership and control
The choice of financing can affect who owns and controls a business.
Issuing additional shares may dilute existing shareholders' ownership and voting rights. Borrowing generally does not transfer ownership, but lenders may impose conditions or covenants that restrict certain financial activities.
Business owners should compare these implications with the amount of capital required and the repayment obligations they can manage.
3. Cash flow position
Cash flow measures the money moving into and out of an individual’s finances or a business. It is important because obligations must be met when payments fall due, not merely when income or profits are recorded.
A business with reliable cash inflows may be better positioned to service debt. A business with seasonal or unpredictable revenue may need more flexible funding.
For individuals, a practical starting point is to list monthly income and expenses, account for debt repayments and set aside money for emergencies. SEBI's investor education guidance also recommends budgeting, prioritising essential expenses and saving for future needs.
4. Fixed operating costs
Fixed operating costs are expenses that generally remain stable over a relevant period, such as rent, certain salaries and insurance premiums. Businesses with substantial fixed costs may have less flexibility when revenue falls.
Taking on additional debt can increase the pressure on cash flow because interest and repayment commitments must still be met. Before borrowing, businesses should consider their break-even point, operating costs and ability to manage a decline in revenue.
5. Cost of raising funds
The cost of financing includes more than the stated interest rate. Businesses may also incur processing, legal, underwriting, documentation and other transaction expenses.
Equity financing can involve issue-related expenses and expectations of future returns from shareholders. Debt financing involves interest and may include fees or security requirements.
Comparing the total cost over the relevant period helps businesses assess whether a financing option is affordable and appropriate for the intended use.
6. Tax considerations
Tax treatment can affect the effective cost of borrowing and the returns from investments. For example, interest expense may be deductible for a business where the applicable tax rules and conditions permit it.
However, tax treatment depends on the type of expense, the business's circumstances and the law in force. Businesses should not assume that every financing expense is deductible. Individuals should also account for the applicable tax treatment when comparing savings and investment products.
7. Market and interest-rate conditions
Changes in interest rates, investor sentiment, market liquidity and economic conditions can affect the availability and cost of financing.
When borrowing costs rise, a business may reconsider the timing of a project or compare alternative funding sources. When investor demand is strong, raising equity may become more feasible, although the outcome depends on the company's circumstances and market conditions.
Financial decisions should be based on current information and realistic assumptions rather than relying solely on past market conditions.
8. Time horizon and financial goals
The time available to achieve a goal influences the type of financial decision that may be appropriate.
A business funding a long-term asset may compare longer-term financing with short-term borrowing. An individual saving for a planned expense within a year may have different liquidity needs from someone planning for retirement over several decades.
Setting a specific goal, estimating the amount required and identifying a realistic timeframe can make it easier to compare options.
9. Liquidity requirements
Liquidity refers to how easily money or an asset can be converted into funds that can be used when needed. A financial choice may offer a return but still be unsuitable if it prevents access to money required for immediate expenses.
Businesses need enough working capital to pay employees, suppliers and other obligations. Individuals may need an emergency fund that is accessible without incurring significant penalties or losses.
Liquidity should be considered alongside potential returns and the cost of accessing funds early.
How can individuals make better financial decisions?
Individuals can use a structured approach to make financial choices more manageable:
Step 1: Understand your current financial position
List your income, essential expenses, discretionary spending, outstanding debt and existing savings. This provides a clearer picture of how much money is available for future goals.
Step 2: Prioritise essential needs and debt obligations
Ensure that essential household expenses and required debt repayments are accounted for before committing money to longer-term goals. Review expensive borrowing carefully and consider the consequences of missed payments.
Step 3: Build an emergency fund
Set aside accessible savings for unexpected expenses, such as urgent repairs or a temporary loss of income. The appropriate amount depends on your household expenses, income stability and responsibilities.
Step 4: Define specific financial goals
Identify what you are saving for, how much you may need and when you will need the money. For example, instead of setting a vague goal to save more, you could plan to set aside Rs. 3,000 each month towards a known expense over the next 12 months.
Step 5: Compare suitable options
Compare available options based on the goal, time horizon, liquidity, costs, tax treatment and risk. A savings account, fixed deposit, mutual fund or insurance product serves a different purpose, so consider the product's actual features rather than relying on the label alone.
Step 6: Review your decisions periodically
Income, expenses, responsibilities and financial goals can change. Review your budget and commitments periodically and adjust your plan when necessary. Avoid making major decisions based only on short-term market movements or promotional claims.
Check out different FD Rates
How can a fixed deposit fit into personal financial decisions?
A fixed deposit (FD) can be considered when an individual has a lump sum to set aside for a specified period and wants to know the applicable interest rate at booking. Whether it is suitable depends on the person's goal, liquidity needs, tax position and tolerance for issuer risk.
For example, after accounting for essential expenses and emergency savings, someone may decide to set aside a separate amount for a planned expense in a few years. A Bajaj Finance FD is one option to compare if the investor is eligible and the available tenure and payout terms match the goal.
Before choosing an FD, consider:
- Tenure: Select a period that aligns with when the money may be needed.
- Interest payout: Compare cumulative deposits with options that pay interest periodically.
- Liquidity: Review the rules and consequences for premature withdrawal.
- Tax: FD interest is generally taxable under applicable income-tax rules.
- Issuer risk: Credit ratings provide an assessment of creditworthiness but do not guarantee repayment. Bajaj Finance company FDs are not covered by DICGC deposit insurance.
An FD is a personal savings option, not a form of corporate financing. A business deciding how to fund operations must assess business-specific sources of capital, their costs and repayment or ownership implications.
Financial decisions shape how individuals manage their money and how businesses allocate capital. Individuals need to consider income, expenses, savings, debt, financial goals and access to funds. Businesses need to evaluate investment opportunities, choose appropriate funding sources and decide how much profit to retain or distribute.
The most suitable decision depends on the objective, available resources, cost, risk and time horizon. By comparing alternatives carefully, using realistic assumptions and reviewing decisions as circumstances change, individuals and businesses can make choices that better support their financial priorities.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What are the three main financial decisions?
The three main corporate finance decisions are investment, financing and dividend decisions. Investment decisions determine how funds are deployed, financing decisions determine how funds are raised, and dividend decisions determine how profits are distributed or retained. Together, they influence a company's growth plans, capital structure and financial position.
What is the meaning of a financing decision?
A financing decision is the process of determining how a business will obtain funds for its operations, investments or expansion. Sources may include equity, loans, bonds, retained earnings and hybrid instruments. The choice depends on factors such as cost, cash flow, repayment capacity, risk and the effect on ownership and control.
What is the difference between a financial decision and a financing decision?
A financial decision is a broad term covering choices about earning, spending, saving, investing, borrowing and managing money. A financing decision is narrower and concerns how funds are raised, particularly by a business. Financing decisions are therefore one part of financial decision-making rather than a synonym for every financial choice.
How does tax affect financing decisions?
Tax rules can influence the effective cost of different funding sources. For example, interest expenses may be deductible for a business where the applicable conditions are met. However, the tax treatment depends on the nature of the expense, the business's circumstances and current law. Businesses should assess the applicable rules before comparing financing alternatives.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.