








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
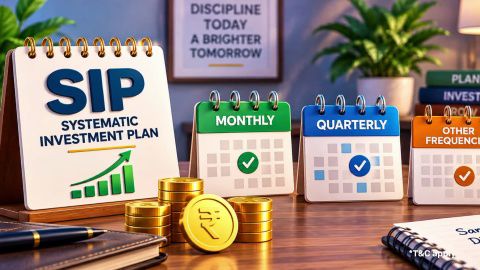
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
The barbell investment strategy combines investments at two contrasting ends of a portfolio while limiting exposure to the middle. For example, an investor may allocate 70% to lower-risk assets and 30% to higher-risk investments.
- The barbell investment strategy limits intermediate exposures.
- Bond barbells combine short-term and long-term maturities.
- Equity portfolios combine relatively stable and higher-risk investments.
- The SEBI Riskometer identifies six mutual fund risk levels.
- SIP investments can start from Rs. 100 monthly.
A barbell portfolio may provide a balance between liquidity and growth potential. However, both ends can experience losses, and the allocation should reflect individual financial goals.
What is the barbell strategy?
The barbell strategy is an investment approach that concentrates a portfolio at two contrasting ends while maintaining limited exposure to intermediate investments. It is commonly used in bond investing and can also be adapted to other asset classes. In a bond portfolio, investors hold short-term and long-term bonds while limiting intermediate maturities. In a broader investment portfolio, they may combine relatively lower-risk assets with higher-risk investments.
How does the barbell strategy work?
The barbell strategy works by concentrating investments at two ends of a risk or maturity spectrum while limiting exposure to intermediate positions. In bond investing, short-term securities provide opportunities to reinvest when they mature. Long-term bonds provide exposure to longer maturities but are generally more sensitive to interest-rate changes. The following table compares two common approaches:
| Bond barbell strategy | Equity mutual fund barbell |
| Short-term bonds provide earlier maturities and reinvestment opportunities. | Relatively diversified large-cap funds form one end. |
| Long-term bonds provide exposure to longer maturities. | Small-cap or thematic funds provide higher-risk exposure. |
| Intermediate bond maturities receive limited allocation. | Intermediate-risk exposures receive limited allocation. |
Illustrative bond reinvestment example:
Suppose an investor purchases a two-year bond worth Rs. 20,000 with a 6% annual coupon. After maturity, the principal becomes available for reinvestment. If a comparable new bond offers 7.5% annually, the investor could reinvest Rs. 20,000 and receive Rs. 1,500 in annual interest instead of Rs. 1,200, assuming the new bond is purchased at face value. These rates are hypothetical. Reinvestment rates may fall, and long-term bond prices can decline when market yields rise. The barbell investment strategy does not guarantee profits or protection against losses.
Which barbell strategy suits you?
A barbell portfolio combining debt and equity mutual funds is one approach Indian investors can evaluate. Bond, equity, and income-oriented versions have different characteristics and risks.
The following table compares five approaches:
| Barbell strategy type | What it includes | Risk profile | Investor objective | SEBI Riskometer level |
| Bond barbell strategy | Short-term and long-term bonds | Interest-rate and credit risks | Manage maturity exposure | Applicable only if implemented through mutual funds |
| Equity barbell | Large-cap and small-cap or thematic funds | Substantial equity-market risk | Long-term growth exposure | Check each scheme; equity schemes can carry High or Very High risk |
| Debt MF barbell | Short-duration and long-duration debt funds | Varying interest-rate and credit risks | Combine different debt maturities | Scheme-specific |
| Income-focused barbell | Short-term debt and longer-term income-generating investments | Income, market, and liquidity risks | Balance income requirements | Scheme-specific where mutual funds are used |
| Equity + Debt MF barbell | Debt mutual funds and higher-risk equity funds | Depends on asset allocation | Combine differing risk exposures | Check the debt and equity scheme Riskometers separately |
Note: These are investment approaches, not SEBI-defined barbell categories. Directly held bonds do not receive mutual fund Riskometer ratings. Actual scheme ratings depend on portfolio holdings and risk characteristics. Investors should review the latest scheme-specific Riskometer instead of assuming a fixed rating for an entire mutual fund category.
What are the benefits and risks?
The barbell strategy can combine liquidity, growth opportunities, and different investment exposures. However, it also requires monitoring and can experience losses when market conditions change.
The following table explains its potential benefits and limitations:
| Advantages | Disadvantages |
| Combines investments with different risk characteristics | Higher-risk assets can experience substantial losses |
| Short-term bonds provide reinvestment opportunities | Reinvestment rates may be lower at maturity |
| Long-term bonds offer exposure to longer maturities | Long-term bond prices can decline when interest rates rise |
| Allows adjustments to asset allocation | Requires monitoring and periodic rebalancing |
| Limits dependence on intermediate exposures | May underperform other portfolio strategies |
Investors may consider the barbell approach when they want exposure to contrasting investment characteristics without allocating heavily to intermediate positions. However, combining different assets does not automatically reduce overall portfolio volatility. The outcome depends on allocation, asset correlation, and market conditions. A barbell portfolio may also experience losses across both ends during unfavourable market periods.
How can you build a barbell portfolio?
You can build a barbell portfolio by identifying financial goals, selecting contrasting investments, deciding their allocation, and reviewing the portfolio periodically.
Follow these steps:
- Define your investment goals: Identify your financial objective, investment horizon, and ability to tolerate potential losses.
- Choose an allocation: Decide how much money to invest at each end. For example, you may consider an illustrative 70:30 debt-equity allocation.
- Select lower-risk investments: Evaluate liquid, overnight, or other suitable debt mutual funds. Review their credit, interest-rate, and liquidity risks.
- Select higher-risk investments: Consider equity categories such as small-cap or thematic funds based on your investment horizon and risk tolerance.
- Complete KYC and invest: Complete the required Know Your Customer (KYC) process before investing. Select suitable schemes and invest through an SIP or lumpsum mode.
- Monitor and rebalance: Review the portfolio periodically. Adjust allocations when market movements or financial requirements change, considering costs and taxes.
What should beginners consider?
Beginners should assess their risk tolerance, investment horizon, and liquidity needs before using a barbell strategy. A portfolio containing both lower-risk and higher-risk assets can still experience substantial losses.
Consider these practical points:
- Start with a manageable allocation: Avoid selecting a high-risk allocation merely because it offers greater growth potential.
- Review individual schemes: Check investment objectives, portfolio holdings, expense ratios, and exit loads.
- Understand concentration risk: Investing heavily in one thematic or sector fund can increase potential losses.
- Maintain emergency savings: Avoid committing money required for immediate financial needs.
- Review periodically: Reassess the allocation when investments or financial goals change.
Conclusion
The barbell investment strategy combines contrasting investment exposures while limiting intermediate positions. In bond investing, it typically involves short-term and long-term securities. Broader portfolios may combine relatively lower-risk debt investments with higher-risk equity investments.
The strategy can provide different reinvestment and growth opportunities, but it does not eliminate market, credit, or interest-rate risks.
Investors should select asset allocations according to their financial goals, liquidity requirements, and risk tolerance. Periodic portfolio reviews can help maintain the intended allocation.
The Bajaj Broking website provides access to mutual fund schemes across different categories, with SIP and lumpsum investment options available for eligible schemes.
Last reviewed: 16 November 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Understanding the barbell strategy
Barbell strategy risks and SIPs
What is an example of a barbell strategy?
An example is investing 70% of a portfolio in short-duration debt investments and 30% in higher-risk equity funds. This illustrative allocation combines different risk exposures but does not guarantee capital protection or positive investment returns.
What is the barbell value strategy?
A barbell value strategy is an informal term for combining investments with contrasting valuation or risk characteristics, such as established value stocks and higher-growth companies. There is no universally prescribed allocation or standard definition for this approach.
How does the barbell strategy differ from diversification?
A traditional diversified portfolio spreads investments across multiple asset classes or risk levels. A barbell strategy deliberately concentrates allocations at two contrasting ends while limiting intermediate exposures. Both approaches involve risks and require suitable asset allocation.
Can the barbell strategy lose money?
Yes, the barbell strategy can lose money when equity markets decline, bond prices fall, or issuers default. Combining contrasting investments does not guarantee protection because both ends of the portfolio can experience losses under certain market conditions.
Is the barbell strategy suitable for beginners?
Beginners can consider a barbell strategy after understanding its risks, allocation requirements, and investment horizon. However, managing contrasting exposures may require additional monitoring. A simpler diversified portfolio may be more appropriate for investors unfamiliar with market risks.
Can I start a barbell SIP with a small amount?
Yes, you can use SIPs to invest in mutual funds selected for a barbell portfolio. On the Bajaj Broking website, eligible schemes permit SIPs from Rs. 100 monthly, subject to scheme-specific investment minimums and availability.
Disclaimer
Bajaj Finance Limited ("BFL"), a non-banking financial company registered with the Reserve Bank of India, is registered with the Association of Mutual Funds in India ("AMFI") as a Mutual Fund Distributor under ARN 90319 and distributing the mutual fund as a sub-distributor of Bajaj Financial Securities Limited (BFSL) registered under ARN-163403. BFL does not independently solicit, source, procure, accept or book any new mutual fund business under its own ARN. Any activities undertaken by BFL in relation to mutual fund products shall be limited to the extent permissible under applicable law and the operating arrangement approved for such products. BFL does not act as an investment adviser or research analyst.
BFL does not:
(i) provide investment advisory services in any manner or form;
(ii) undertake any customised or personalised suitability assessment;
(iii) conduct independent research or analysis in relation to any mutual fund scheme or other investment; or
(iv) provide any assurance or guarantee regarding returns, capital protection or performance. Participation in mutual fund products is entirely voluntary.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice.
Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates.
The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund.
BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Riskometer: The Riskometer is only one indicator of the risk associated with a mutual fund scheme. Before investing, investors should evaluate the scheme with reference to the applicable product labelling and Riskometer as well as other quantitative and qualitative factors, including performance, portfolio composition, fund manager and asset manager. Investors who are uncertain about the suitability of a scheme should consult their professional advisers before investing.
Disclosure: BFL holds AMFI Registration Number 90319. BFL does not independently solicit or book new mutual fund business under its own ARN. Accordingly, references on this platform to mutual fund schemes of Bajaj Finserv Asset Management Limited ("BFSAMC"), a group company of BFL, or of any other Asset Management Company shall not be construed as solicitation, sourcing, procurement, acceptance or booking of new mutual fund business by BFL under ARN 90319. BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.