
Everything You Need to Know About Flexi Loans

Everything You Need to Know About Flexi Loans

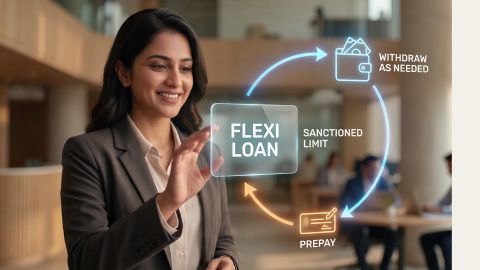
A Flexi Loan lets you withdraw funds from a sanctioned loan limit as needed and pay interest on the amount withdrawn, while allowing eligible part-prepayments without additional part-prepayment charges.

Rs. 40,000 - Rs. 55 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


Last updated: September 2026


In Summary

A Flexi Loan can suit you when your expenses arise in stages and you do not want to withdraw the entire sanctioned amount at once. Bajaj Finance offers Flexi Dropline Loan and Flexi Hybrid Loan variants alongside the Term Loan option.


  • You can withdraw funds multiple times from your sanctioned Flexi loan limit.
  • Interest is charged only on the amount you withdraw, not the unused limit.
  • The Flexi Hybrid Loan provides interest-only EMIs during the initial tenure.
  • The initial tenure for the Flexi Hybrid Loan can be up to 36 months, followed by a subsequent tenure of up to 72 months.
  • Flexi Dropline Loan EMIs include both principal and interest on the withdrawn amount.
  • Flexi Dropline and Flexi Hybrid Loans do not have part-prepayment charges under the stated product terms.
  • The loan amount can range from Rs. 40,000 to Rs. 55 lakh, subject to eligibility and applicable terms.
  • Flexi facility charges apply to Flexi variants and are deducted upfront from the loan amount.

You should compare the repayment structure, maintenance charges, Flexi facility charges and prepayment terms before choosing a variant.

What is a Flexi Loan?

A Flexi Loan is a personal loan facility that gives you a sanctioned limit from which you can withdraw funds as required. You pay interest only on the amount you actually withdraw.


For example, if your sanctioned limit is Rs. 5 lakh but you initially withdraw Rs. 2 lakh, interest is charged on the withdrawn amount rather than the unused Rs. 3 lakh, subject to the applicable calculation method and terms.


You can make additional withdrawals when you need funds and make part-prepayments when you have surplus money. The available limit changes as you withdraw and repay.

Show More Show Less

How does a Flexi Loan work?

A Flexi Loan works through a sanctioned limit rather than requiring you to take the entire loan amount at once.


  1. You receive a sanctioned limit: Your available limit is determined based on your eligibility and applicable assessment.
  2. You withdraw funds: You can withdraw only the amount you need from the sanctioned limit.
  3. Interest applies to the withdrawn amount: You pay interest on the amount you use.
  4. You repay through the applicable EMI structure: The repayment structure depends on whether you choose Flexi Dropline or Flexi Hybrid.
  5. You can withdraw again: Subject to the available limit and applicable terms, you can make further withdrawals.
  6. You can part-prepay: Flexi variants allow part-prepayment without part-prepayment charges under the stated product terms.

This structure can be useful when you expect expenses to arise at different times.

Show More Show Less

What are the types of Flexi Loans?

Bajaj Finance offers two Flexi variants: Flexi Dropline Loan and Flexi Hybrid Loan. You can also choose a Term Loan, where the sanctioned amount is disbursed at once and repaid through fixed EMIs.


Flexi Dropline Loan


Feature Description
InstalmentFixed EMIs that cover both the principal and interest on the withdrawn amount
Tenure12 months to 108 months 
Annual maintenance chargesUp to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges
Part-prepayment facilityNo part-prepayment charges
Full Pre-payment

Up to 4.72%  (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of Full Pre-Payment.


Flexi facility charges

Flexi Loans – Up to Rs 1,999 to Rs 18,999/- (Inclusive of applicable taxes)


Will be deducted upfront from loan amount.


Loan amountRs. 40,000 to Rs. 55 lakh
DisbursalWithdraw and prepay conveniently from your sanctioned loan limit

Flexi Hybrid Loan


Feature Description
InstalmentInterest-only EMIs for the initial part of the loan tenure. EMI applicable only on the withdrawn amount
TenureInitial tenure: Up to 36 months, Subsequent tenure: Up to 72 months
Annual maintenance chargesUp to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit during Subsequent Tenure
Part-prepayment facilityNo part-prepayment charges
Full Pre-paymentUp to 4.72% (inclusive of applicable taxes) on the outstanding loan amount, as on the date of full pre-payment.
Flexi facility charges

Flexi Loans – Up to Rs 1,999 to Rs 18,999/- (Inclusive of applicable taxes)


Will be deducted upfront from loan amount.


Loan amountRs. 40,000 to Rs. 55 lakh
DisbursalWithdraw and prepay conveniently from your sanctioned loan limit

Term Loan

Feature Description
InstalmentFixed EMIs that cover both the principal and interest
Tenure12 months to 108 months 
Annual maintenance chargesNot applicable
Part-prepayment facilityUp to 4.72% (inclusive of applicable taxes) of the principal amount of loan prepaid on the date of such part-prepayment.
 Full Pre-paymentUp to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment.
Flexi facility chargesNo Flexi facility charges.
Loan amountRs. 40,000 to Rs. 55 lakh
DisbursalSingle disbursement of the loan amount

✅  Check your pre-approved loan offer with phone number and OTP → Apply online in 5 minutes → Receive funds within 24 hours*.

Show More Show Less

How is a Flexi Loan different from a Term Loan?

The main difference is how you access and repay the sanctioned amount. A Term Loan provides the full loan amount upfront and uses fixed EMIs covering principal and interest. Flexi variants allow multiple withdrawals from a sanctioned limit.


FactorFlexi LoanTerm Loan
Fund accessWithdraw as requiredFull amount disbursed upfront
InterestOn amount withdrawnOn the loan amount
Multiple withdrawalsAvailable, subject to applicable termsNot applicable
Part-prepaymentNo charges for Flexi variantsCharges may apply
EMIDepends on Flexi variantPrincipal + interest
Flexi facility chargeApplicableNot applicable
Annual maintenance chargeApplicableNot applicable

A Term Loan can be more straightforward when you know the full amount you need at the beginning. A Flexi Loan can be considered when your expenses arise over time.

Show More Show Less

Which Flexi Loan should you choose?

The suitable variant depends on your cash-flow pattern and preferred EMI structure.


Choose a Flexi Dropline Loan if you want:

  • Multiple withdrawals from a sanctioned limit.
  • EMIs that cover principal and interest.
  • The ability to make part-prepayments without part-prepayment charges.
  • Access to funds as expenses arise.

Consider a Flexi Hybrid Loan if you want:

  • Multiple withdrawals.
  • Interest-only EMIs during the initial tenure.
  • Principal repayment to begin after the initial period.
  • The ability to make part-prepayments without part-prepayment charges.

Consider a Term Loan if you need the full amount upfront and prefer fixed EMIs covering principal and interest from the beginning.


Your choice should account for the total repayment cost, not only the initial EMI.

Show More Show Less

What is the loan amount, interest rate and EMI?

A Bajaj Finance Personal Loan, including the Flexi variants, offers Rs. 40,000 to Rs. 55 lakh, subject to eligibility and applicable terms. Interest rates range from 10% to 30.5% per annum, and the repayment tenure runs from 12 months to 108 months. The amount available to you depends on your income, existing EMIs, credit profile and requested amount.


Because interest is charged only on the amount you draw, your cost tracks your usage. For example, if you have a sanctioned limit of Rs. 5 lakh and withdraw Rs. 3 lakh at 13% per annum, interest is charged on Rs. 3 lakh, not Rs. 5 lakh. Under the Hybrid variant, the interest-only EMI on that Rs. 3 lakh is about Rs. 3,250 per month during the initial tenure, compared with a full equated monthly instalment (EMI) of about Rs. 10,108 on a 36-month term loan, so the early outgo is lower. These figures exclude applicable fees and are illustrative.


Eligible customers may receive funds within 24 hours after approval, subject to document verification and applicable terms. You can check your eligibility using only your mobile number and OTP, without visiting a branch.

Show More Show Less

What are the advantages and limitations of Flexi Loans?

A Flexi Loan can be useful when your funding requirement is not a single one-time expense. However, you should also account for the charges and repayment structure.

AdvantagesLimitations
Multiple withdrawals from the sanctioned limitFlexi facility charges apply
Interest on the amount withdrawnAnnual maintenance charges apply
No part-prepayment charges for Flexi variantsFull prepayment can attract charges
Access to funds as expenses ariseUnused limit is available but does not represent cash already received
Interest-only EMI option under Flexi Hybrid during initial tenurePrincipal repayment begins later under the Hybrid structure
Can part-prepay when you have surplus fundsTotal cost depends on withdrawals, usage period and applicable charges

The right choice depends on whether the flexibility provides enough value for your expected borrowing pattern.

Show More Show Less

What should you check before taking a Flexi Loan?

Before taking a Flexi Loan, you should check:


  1. Limit and need: Confirm the sanctioned limit and how much you need to draw.
  2. Interest rate: Confirm the applicable interest rate and how interest is charged on your usage.
  3. EMI structure: Check the EMI structure, especially the interest-only period under the Hybrid variant.
  4. Charges: Review the processing, prepayment and any Flexi-facility charges that apply.
  5. Tenure: Compare tenures on both the EMI and the total interest.
  6. Prepayment plan: Plan how and when you will prepay to reduce your interest cost.
  7. Eligibility: Check whether you meet the applicable eligibility criteria.

Meeting the eligibility criteria does not by itself confirm approval, which remains subject to verification and applicable terms.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Overview

What is a flexi loan?

A Flexi Loan is a personal loan facility that allows you to withdraw funds from a sanctioned loan limit as needed. Interest is charged on the amount you withdraw, subject to the applicable terms.

A Flexi Hybrid Loan can provide interest-only EMIs during the initial tenure, followed by principal-and-interest EMIs. A Flexi Dropline Loan uses EMIs covering both principal and interest on the withdrawn amount.

The Flexi Loan amount can range from Rs. 40,000 to Rs. 55 lakh, subject to eligibility and applicable terms. You can check your eligibility using only your mobile number and OTP, without visiting a branch.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000