







Invest in equities, F&O and upcoming IPOs effortlessly by opening a demat account online. Enjoy a free subscription for the first year with Bajaj Broking

Know the benefits of a demat account
Check now
Free Demat account in minutes | Low brokerage | Online account opening
In summary
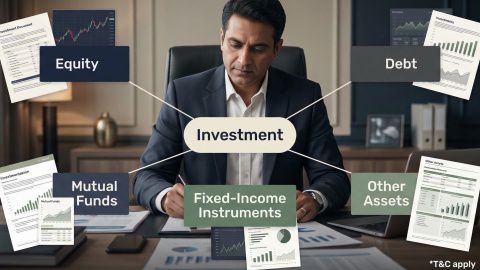
Basics of Investment
Investment can help you use your spare money for future goals instead of keeping all of it idle. However, every investment has some form of risk, cost, or restriction.
- People invest for goals such as education, a home, retirement, or building long-term wealth.
- Saving and investing are different. Savings usually focus on access and stability, while investments may involve more risk.
- Common investment options include fixed deposits, shares, mutual funds, bonds, gold-related products, Sovereign Gold Bonds, and real estate.
- Higher potential return generally comes with higher uncertainty.
- Compounding can help money grow when returns remain invested.
- Diversification reduces dependence on one investment but cannot prevent every loss.
- Before choosing an option, check safety, return potential, liquidity, time horizon, costs, and tax treatment.
Show More
Show Less
What is investment?
Investment means putting money into an asset or financial product with the aim of meeting a future financial goal.
You give up the use of some money today because you expect that money to provide value in the future.
That value may come through:
- an increase in the asset's price,
- interest,
- dividends,
- rental income, or
- a combination of these.
A simple example
Suppose you have:
₹10,000
You could keep the ₹10,000 as cash.
Or you could put part of it into an investment.
If that investment increases in value, your money may grow. If its value falls or the issuer cannot meet its obligations, you may also lose money.
This is the first basic rule of investing:
Return and risk come together.
Investment is therefore different from simply looking for the option that promises the biggest number.
The Securities and Exchange Board of India (SEBI) advises investors to consider their financial goals, investment period, risk appetite, liquidity, and knowledge
before investing.
Source: Securities and Exchange Board of India (SEBI)
Show More
Show Less
Why do people invest money?
People invest money mainly to achieve future financial goals and help protect their purchasing power over time.
For example, a person may invest for:
- children's education,
- buying a home,
- retirement,
- future family expenses,
- building long-term wealth, or
- another planned financial goal.
Inflation also matters
Inflation means that the prices of goods and services can increase over time.
Suppose a household expense costs: ₹1,000 today
If prices rise over the years, the same ₹1,000 may buy fewer goods later.
Investment can help your money grow, although no investment guarantees that it will always beat inflation.
Investment can also generate income
Some investments can provide periodic income.
Examples include:
- interest from certain deposits or bonds,
- dividends from shares, when declared, and
- rent from property.
The income is not automatically guaranteed in every investment.
For example, a company can reduce or stop an equity dividend
Show More
Show Less
Current IPO
Mainboard
SME
BLS POLYMERS LIMITED
Bidding period
29 Oct 2026- 27 Oct 2026
Minimum investment
₹14,200 / 13 Lot
SFC ENVIRONMENTAL TECHNOLOGIES LIMITED
Bidding period
29 Oct 2026- 27 Oct 2026
Minimum investment
₹14,085 / 13 Lot
M K SONS FINE JEWELS LIMITED
Bidding period
30 Oct 2026- 28 Oct 2026
Minimum investment
₹13,923 / 13 Lot
BOMBAY COATED AND SPECIAL STEELS LIMITED
Bidding period
02 Nov 2026- 29 Oct 2026
Minimum investment
₹14,196 / 13 Lot
WISCON INDUSTRIES LIMITED IPO
today
Bidding period
27 Oct 2026 -
29 Oct 2026
Minimum investment
₹1,16,400 / 1 Lot
AJWA PROJECTS LIMITED IPO
Bidding period
28 Oct 2026 -
30 Oct 2026
Minimum investment
₹1,21,800 / 1 Lot
CARVER ROBOWELD LIMITED IPO
Bidding period
28 Oct 2026 -
30 Oct 2026
Minimum investment
₹1,21,600 / 1 Lot
ANTALA INDUSTRIES LIMITED IPO
Bidding period
29 Oct 2026 -
02 Nov 2026
Minimum investment
₹1,26,000 / 1 Lot
MAXWELL ENGINEERING SOLUTIONS LIMITED IPO
Bidding period
30 Oct 2026 -
03 Nov 2026
Minimum investment
₹1,20,000 / 1 Lot
How is investing different from saving?
Saving focuses mainly on keeping money available, while investing usually involves putting money into an asset to achieve a future goal.
| Point | Saving | Investing |
|---|---|---|
| Main purpose | Keep money available | Try to grow money or earn income |
| Risk | Usually lower depending on where money is held | Depends on the investment |
| Time period | Often short term | Can be short, medium, or long term |
| Value | Usually more stable | May rise or fall |
Example
Suppose Raju has: ₹30,000
He may need ₹10,000 at short notice for medical or vehicle expenses.
Keeping that entire emergency amount in a volatile investment could cause a problem if its value falls when he needs it.
He might therefore keep emergency money accessible and consider investing only money that fits a longer-term goal.
Saving and investing can work together
You do not have to choose one and completely ignore the other.
Savings can provide:
- emergency access,
- short-term stability, and
- money for near-term expenses.
Investments can then serve longer-term goals according to your ability to take risk.
SEBI advises people to maintain money for day-to-day expenses and emergencies before committing money to investments.
Show More
Show Less
What investment options are available in India?
India offers investment options with very different levels of risk, liquidity, cost, and return structure.
The main options discussed in the basics of investment include fixed deposits, shares, mutual funds, bonds, gold-related products, Sovereign Gold Bonds, and real estate.
| Investment option | How money may grow | Main point to check | Liquidity |
| Fixed deposit | Interest | Rate, tenure, bank, withdrawal terms | Depends on deposit terms |
| Shares | Price increase or dividends | Company and market risk | Usually market-linked |
| Mutual funds | Fund portfolio performance | Scheme type and risk | Depends on scheme |
| Bonds | Interest and repayment | Credit and interest-rate risk | Can vary |
| Gold-related investments | Gold-price movement | Product structure and regulation | Depends on product |
| Real estate | Price rise or rent | Cost, location, saleability | Usually lower |
Fixed deposits
A fixed deposit, or FD, allows you to deposit money with a bank or other eligible financial institution for a specified period.
You receive interest according to the applicable terms.
Check:
- interest rate,
- tenure,
- premature-withdrawal rules,
- institution, and
- deposit protection.
For deposits with insured banks, the Deposit Insurance and Credit Guarantee Corporation (DICGC) currently provides insurance of up to ₹5 lakh per depositor per bank, including principal and interest, subject to applicable conditions.
This does not mean every product called a “fixed deposit” carries exactly the same protection.
Shares
A share represents ownership in a company.
If you buy 10 shares at ₹500 each
your investment value is ₹5,000
If the market price later becomes ₹600, the market value becomes ₹6,000.
If it falls to ₹400, the market value becomes ₹4,000.
Shares therefore offer the possibility of price appreciation but also carry the risk of loss.
A company may also pay dividends, but dividends are not guaranteed.
Mutual funds
A mutual fund pools money from many investors and invests it according to a stated investment objective.
Depending on the scheme, the fund may invest in:
- shares,
- bonds,
- money-market instruments, or
- a mix of assets.
You receive units of the mutual fund.
You do not directly become a shareholder of every company held by the fund.
Different mutual funds can have very different levels of risk.
Bonds and debentures
A bond or debenture is a debt instrument.
When you buy one, you are effectively lending money to the issuer under specified terms.
Check:
- interest or coupon,
- maturity,
- issuer creditworthiness,
- whether it is secured or unsecured,
- liquidity, and
- interest-rate risk.
A fixed coupon does not mean the investment is free from risk.
Gold and gold-related investments
Gold can be held through different structures.
These can include:
- physical gold,
- Gold Exchange Traded Funds,
- Electronic Gold Receipts, where applicable, and
- other gold-linked products.
The structure matters because the risks and regulation are different.
SEBI stated in November 2025 that digital gold offered by some online platforms is outside its securities-market regulatory framework and may expose investors to counterparty and operational risks.
Digital gold should therefore not simply be described as a “safe and secure” investment.
Sovereign Gold Bonds
Sovereign Gold Bonds, or SGBs, are Government of India securities denominated in grams of gold.
For existing SGB issuances:
- maturity is 8 years, and
- premature redemption through the prescribed RBI process is permitted after the fifth year on specified interest-payment dates.
The bonds can also be held in dematerialised form where applicable.
SGBs provide exposure linked to gold prices but are not the same as owning physical gold.
Real estate
Real estate includes residential, commercial, or other property.
Returns may come from:
- rental income, or
- an increase in the property's value.
However, property can require a large amount of money and may take time to sell.
Other costs may include:
- maintenance,
- registration,
- taxes,
- loan interest, and
- repairs.
Sources:
- Securities and Exchange Board of India (SEBI)
- Reserve Bank of India (RBI)
- Deposit Insurance and Credit Guarantee Corporation (DICGC)
Show More
Show Less
How do risk and return work?
Risk means there is a possibility that the actual result will be different from what you expected, including losing some or all of your money.
Return is the gain or income you receive from an investment.
In general, investments offering higher potential returns also tend to involve greater uncertainty.
Common investment risks
- Market risk: The value of an investment may fall because market prices change.
- Credit risk: An issuer may fail to make an interest or repayment due.
- Liquidity risk: You may find it difficult to sell an investment quickly at a reasonable price.
- Inflation risk: Your investment may grow more slowly than the cost of living.
- Business risk: A company's sales, profits, debt, or operations may weaken.
Example
Suppose you have two choices.
Investment A changes very little in value but offers limited growth potential.
Investment B can rise much faster but can also fall sharply.
The second option is not automatically better.
The right choice depends on:
- why you need the money,
- when you need it, and
- how much loss you can handle.
Risk is personal
A 25-year-old investing for retirement may be able to tolerate short-term fluctuations differently from someone who needs the money for school fees next year.
Risk tolerance therefore cannot be decided only by age or income.
Show More
Show Less
Start investing today

Open Demat Account
Open Trading Account

Margin Trading Facility
How does compounding help money grow?
Compounding happens when returns remain invested and can themselves generate further returns.
This can make time important in long-term investing.
Simple example
Suppose: Original investment: ₹10,000
After one period, its value grows to ₹11,000
If you leave the full ₹11,000 invested, the next return is calculated on ₹11,000 rather than only on the original ₹10,000.
That extra ₹1,000 has now joined your original money.
This process can repeat.
Does compounding guarantee wealth?
No. Compounding magnifies whatever happens to the investment.
If returns are positive and remain invested, compounding can increase growth.
If an investment suffers losses, its value can also fall.
Market-linked investments do not provide a fixed annual return simply because compounding exists.
Time matters
Longer periods give compounding more opportunities to work.
However, the final result still depends on:
- actual returns,
- fees,
- taxes,
- withdrawals, and
- losses.
Upcoming IPO
Mainboard
SME
Aarvee Engineering Consultants Limited
Bidding
To
be announced
Price
To be announced
Abakkus Asset Manager Limited
Bidding
To
be announced
Price
To be announced
Absolute Project India Limited
Bidding
To
be announced
Price
To be announced
Advanced SysTek Limited
Bidding
To
be announced
Price
To be announced
Advanta Enterprises Limited
Bidding
To
be announced
Price
To be announced
Why is diversification important?
Diversification means spreading money across different investments instead of depending entirely on one asset.
It can reduce the damage caused by one poor-performing investment.
Example
Suppose you invest ₹1 lakh
entirely in one company's shares.
If those shares fall by 40%
your investment value becomes ₹60,000
Now imagine the ₹1 lakh was divided among several different investments.
A fall in one investment may still hurt, but the entire portfolio does not depend on that one company.
Diversification can happen in two ways
You can diversify within an asset class.
For example, you may hold shares in companies from different industries instead of only one company.
You can also diversify across asset classes.
For example:
- equity,
- debt,
- gold-related investments, and
- other suitable assets.
Does diversification stop all losses?
No. Diversification reduces concentration risk.
It cannot prevent losses when several assets or the wider market fall together.
The aim is to avoid making the success of your entire financial plan depend on one investment.
How do you choose an investment option?
Choose an investment by matching its features with your goal rather than choosing only by return.
A useful way to compare options is through five questions.
1. When will you need the money?
Money needed next year should not automatically be treated like money meant for retirement 20 years away.
This is your time horizon.
2. How much loss can you handle?
Ask what would happen if your ₹50,000 investment temporarily became ₹40,000
Would you still be able to meet your financial needs?
If not, the investment may be too volatile for that particular goal.
3. How quickly can you get your money back?
Some investments can be sold or redeemed relatively quickly. Property can take much longer.
4. What can reduce your return?
Check:
- brokerage,
- management fees,
- exit charges,
- taxes,
- interest costs, and
- other applicable expenses.
A return shown before costs is not necessarily what reaches your pocket.
5. Do you understand the product?
Do not invest only because:
- a friend recommended it,
- its price recently increased,
- an advertisement calls it safe,
- it offers a high interest rate, or
- everyone around you is buying it.
Understand how your money can make a return and how you can lose money.
SEBI advises investors to consider safety, returns, liquidity, risk, time horizon, tax, and investment knowledge when choosing an investment.
Features and Benefits of LAS

Tenure 36 months
Flexible repayment from 7 days to 36 months

1000+ shares
Get 50% value on 1000+ shares

All DP shares available
All companies’ and DPs’ Demat accounts accepted for loans

Customer portal
Handle loans, shares, and statements — all in one place
What mistakes should a beginner avoid?
Beginners can avoid many losses by refusing to make decisions they do not understand.
Putting emergency money into risky investments
Money needed for rent, food, school fees, medical expenses, or emergencies should not depend on tomorrow's market price.
Chasing recent returns
An investment that performed well last year may not perform the same way this year.
Past performance does not guarantee future returns.
Putting everything in one place
One stock, one sector, one property, or one asset class can create concentration risk.
Believing high returns come without risk
A promise of unusually high returns with little or no risk should be treated carefully.
Risk and return are connected.
Ignoring charges
Small costs can add up over time.
Always check applicable charges before investing.
Investing in something you cannot explain
If you cannot explain in simple words how an investment works, how it makes money, and what can cause a loss, learn more before investing.
Using borrowed money without understanding the risk
Borrowing to invest can magnify losses because the loan still needs to be repaid even if the investment falls.
Following unverified tips
Social-media messages, messaging groups, friends, and strangers can provide inaccurate or misleading information.
For securities-market investments, verify information through official sources and use registered intermediaries where required.
Pro Tip
Top Investment Options for You
Related Articles
Frequently Asked Questions
Basics of Investment
What is the 5% rule in investing?
The 5% rule is a general diversification guideline that suggests you should avoid putting more than 5% of your portfolio into a single investment. The idea is to limit the impact if one investment performs poorly. However, this is not a fixed rule for every investor. Your allocation should depend on your goals, risk tolerance, investment horizon, and overall portfolio strategy.
What is the basic concept of investment?
Investment means putting your money into an asset with the aim of earning income or increasing its value over time. You may invest in options such as fixed deposits, bonds, mutual funds, shares, gold, or real estate. Each option carries different levels of risk and potential return, so you should choose investments based on your financial goals, time horizon, and ability to take risk.
Disclaimer
Investments in the securities market are subject to market risk, read all related documents carefully before investing.
Broking services offered by Bajaj Financial Securities Limited (Bajaj Broking). Reg Office: Bajaj Auto Limited Complex, Mumbai –Pune Road Akurdi Pune 411035. Corporate Office: Bajaj Financial Securities Limited, 1st Floor, Mantri IT Park, Tower B, Unit No 9 & 10, Viman Nagar, Pune, Maharashtra 411014. SEBI Registration No.: INZ000218931 | BSE Cash/F&O/CDS (Member ID:6706) | NSE Cash/F&O/CDS (Member ID: 90177) | MCX (Member ID: 57680) | DP registration No: IN-DP-418-2019 | CDSL DP No.: 12088600 | NSDL DP No. IN304300 | AMFI Registration No.: ARN –163403.
Details of Compliance Officer: Mr. Harinatha Reddy Muthumula (For Broking/DP/Research) | Email: compliance_sec@bajajbroking.in | Contact No.: 020-4857 4486. For any investor grievances write to compliance_sec@bajajbroking.in/ compliance_dp@bajajbroking.in (DP related)
This content is for educational purpose only. Securities quoted are exemplary and not recommendatory.
Research Services are offered by Bajaj Broking as Research Analyst under SEBI Regn: INH000010043.
For more disclaimer, check here: https://www.bajajbroking.in/disclaimer