







Invest in equities, F&O and upcoming IPOs effortlessly by opening a demat account online. Enjoy a free subscription for the first year with Bajaj Broking

Know the benefits of demat account
Check Now
Free Demat account in minutes | Low brokerage | Online account opening
In summary
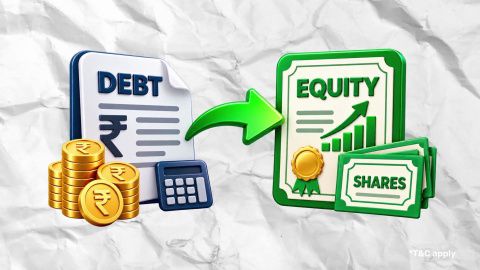
Debt Equity Swap
A debt-equity swap allows a company to replace part of its debt with equity issued to creditors. This can reduce future debt repayments and interest obligations, but existing shareholders may own a smaller percentage of the company afterwards.
- Debt converts into company ownership shares.
- Outstanding debt falls after the conversion.
- Equity rises as new shares are issued.
- Existing shareholders may face ownership dilution.
- EPS may change after share issuance.
- Creditors accept equity instead of repayment.
Show More
Show Less
What is a debt-equity swap?
A debt-equity swap is an arrangement in which a company exchanges some of its outstanding debt for equity ownership.
Instead of receiving repayment for the agreed portion of debt, a creditor receives shares, or another agreed equity interest in the company.
The transaction changes the company's capital structure because:
| Before the swap | After the swap |
| Higher outstanding debt | Lower outstanding debt |
| Lower equity from the transaction | Higher equity from new issuance |
| Creditors are lenders | Participating creditors become shareholders |
| Existing ownership based on fewer shares | Ownership may be spread across more shares |
The exact legal and financial structure depends on the agreement and applicable regulations.
Show More
Show Less
Why should shareholders understand a debt-equity swap?
A debt-equity swap can change both a company's finances and your ownership percentage.
The company may carry less debt after the transaction. However, issuing new shares to creditors can dilute existing shareholders.
For an investor, therefore, the important question is not simply whether debt falls. You also need to understand how much equity is issued and what happens to earnings per share (EPS).
Show More
Show Less
Current IPO
Mainboard
SME
How does a debt-equity swap work?
The company and its creditors first agree on how much debt will be converted and the terms of the equity issuance.
Consider a simplified example.
A company has total outstanding debt of ₹50 crore. Its creditors agree to convert ₹20 crore into equity.
Assume, only for illustration, that the agreed conversion price is ₹100 per share.
Number of new shares = Debt converted ÷ Conversion price
₹20 crore ÷ ₹100 = 20 lakh shares
The company therefore issues 20 lakh shares to the participating creditors.
Its debt covered by the example falls from:
₹50 crore − ₹20 crore = ₹30 crore
The creditors no longer hold the converted ₹20 crore as debt. They instead hold equity under the agreed terms.
The ₹100 conversion price in this example is purely hypothetical. Actual conversion pricing depends on the transaction structure and applicable legal and regulatory requirements.
Show More
Show Less
Start investing today

Open Demat Account
Open Trading Account

Margin Trading Facility
What changes after debt becomes equity?
Three areas usually require attention: debt obligations, equity and financial ratios.
Debt on the balance sheet falls
The portion converted into equity is no longer outstanding as debt.
In the example, debt falls from ₹50 crore to ₹30 crore.
This can reduce debt-servicing requirements associated with the converted amount. It does not automatically mean that the company's overall financial position is healthy.
Equity increases
New equity is issued to creditors under the swap.
Those creditors therefore become shareholders for the converted portion and take on risks associated with equity ownership.
Financial ratios can change
Reducing debt and increasing equity can lower the company's debt-to-equity ratio.
However, ratios should not be viewed in isolation. Cash flow, operating performance, profitability and the remaining debt obligations continue to matter.
Show More
Show Less
How does a debt-equity swap affect existing shareholders?
Existing shareholders can face ownership dilution when the company issues additional shares.
Suppose a company initially has 50 crore shares outstanding. It then issues another 10 crore shares to creditors.
Total shares become:
50 crore + 10 crore = 60 crore shares
An investor who owned 1% of the company before the issue would own less than 1% afterward if that investor did not receive additional shares.
This happens because the same holding represents a smaller proportion of the expanded share capital.
Show More
Show Less
Upcoming IPO
Mainboard
SME
Aarvee Engineering Consultants Limited
Bidding
To
be announced
Price
To be announced
Abakkus Asset Manager Limited
Bidding
To
be announced
Price
To be announced
Absolute Project India Limited
Bidding
To
be announced
Price
To be announced
Advanced SysTek Limited
Bidding
To
be announced
Price
To be announced
Advanta Enterprises Limited
Bidding
To
be announced
Price
To be announced
Does a debt-equity swap always reduce EPS?
No. Issuing more shares can put downward pressure on EPS, but the final effect depends on what happens to the company's earnings.
Assume a company earns ₹200 crore and initially has 50 crore shares.
EPS before the swap = ₹200 crore ÷ 50 crore shares = ₹4 per share
If the company issues another 10 crore shares and its earnings remain unchanged:
EPS after the swap = ₹200 crore ÷ 60 crore shares = about ₹3.33 per share
EPS therefore falls in this simplified example.
But EPS does not always fall by the same amount as dilution suggests. If converting debt reduces interest expense and increases future profit, part or all of the dilution effect may be offset.
This is why investors should examine both the new share count and post-restructuring earnings.
Show More
Show Less
Can a lower debt balance make the company safer?
A lower debt balance can reduce some financial obligations, but it does not remove business risk.
A company may still face:
- weak operating cash flow;
- falling revenue or profit;
- remaining debt repayments;
- refinancing requirements;
- shareholder dilution; and
- execution problems in its restructuring plan.
A debt-equity swap changes how a company is financed. It does not by itself repair the underlying business.
Why would creditors accept shares instead of cash?
Creditors may agree to equity when restructuring debt is considered preferable to continuing with the original repayment arrangement.
After conversion, their position changes materially.
A lender normally expects contractual debt repayment and interest, subject to the borrower's ability to pay. An equity holder instead participates in the future value of the company and bears equity-related risk.
Creditors may therefore gain if the company's value later increases. They can also suffer losses if the business performs poorly.
How can a debt-equity swap be initiated?
A debt-equity conversion may form part of a negotiated restructuring between a company and its creditors.
It can also occur under a formal insolvency or resolution process where the approved restructuring provides for creditors to receive equity.
For listed entities, conversions and share issuances can also involve securities-law requirements covering matters such as issuance, pricing, disclosures and changes in shareholding.
Securities and Exchange Board of India rules have recognised debt-to-equity conversion in restructuring contexts, although the requirements depend on the transaction structure.
What should investors check after a debt-equity swap?
Do not judge the transaction only by the fall in debt.
Check these figures together:
| What to check | Why it matters |
| Debt converted | Shows how much liability changes |
| Debt remaining | Shows obligations still outstanding |
| New shares issued | Indicates potential dilution |
| Conversion price | Determines shares issued for converted debt |
| Post-swap ownership | Shows changes in shareholder percentages |
| Interest expense | May fall if debt reduces |
| Profit after restructuring | Influences the final EPS effect |
| Cash flow | Shows whether operations generate cash |
What this means
A debt-equity swap can improve one part of the balance sheet while creating a different trade-off for shareholders.
Less debt can mean lower servicing requirements. More shares can mean greater dilution. The useful assessment therefore combines debt, earnings, cash flow and ownership changes.
Conclusion
A debt-equity swap converts part of a company’s debt into equity, reducing the amount it must repay as debt. However, issuing new shares can dilute existing shareholders and may affect earnings per share. The final impact depends on the conversion terms, remaining debt, interest savings, future profits, and cash flow. Investors should therefore look beyond the lower debt figure and assess how the swap changes ownership, earnings, financial ratios, and the company’s overall ability to operate sustainably.
Features and Benefits of LAS

Tenure 36 months
Flexible repayment from 7 days to 36 months

1000+ shares
Get 50% value on 1000+ shares

All DP shares available
All companies’ and DPs’ Demat accounts accepted for loans

Customer portal
Handle loans, shares, and statements — all in one place
Pro Tip
Top Investment Options for You
Related Articles
Frequently Asked Questions
Debt/Equity Swap
What is a debt-equity swap?
A debt-equity swap converts an agreed amount of a company's debt into equity ownership. The creditor gives up its debt claim for that portion and receives shares, or another agreed equity interest instead.
The company's debt falls while its equity increases. The precise structure, pricing and approvals depend on the transaction and applicable rules.
Does debt-equity swap affect EPS?
It can. If a company issues additional shares and total profit remains unchanged, earnings are divided among more shares and EPS falls.
However, debt conversion can also reduce interest expense. If this increases future profit, the effect on EPS may be partly or fully offset. The actual outcome therefore depends on both earnings and the new share count.
Disclaimer
Investments in the securities market are subject to market risk, read all related documents carefully before investing.
Broking services offered by Bajaj Financial Securities Limited (Bajaj Broking). Reg Office: Bajaj Auto Limited Complex, Mumbai –Pune Road Akurdi Pune 411035. Corporate Office: Bajaj Financial Securities Limited, 1st Floor, Mantri IT Park, Tower B, Unit No 9 & 10, Viman Nagar, Pune, Maharashtra 411014. SEBI Registration No.: INZ000218931 | BSE Cash/F&O/CDS (Member ID:6706) | NSE Cash/F&O/CDS (Member ID: 90177) | MCX (Member ID: 57680) | DP registration No: IN-DP-418-2019 | CDSL DP No.: 12088600 | NSDL DP No. IN304300 | AMFI Registration No.: ARN –163403.
Details of Compliance Officer: Mr. Harinatha Reddy Muthumula (For Broking/DP/Research) | Email: compliance_sec@bajajbroking.in | Contact No.: 020-4857 4486. For any investor grievances write to compliance_sec@bajajbroking.in/ compliance_dp@bajajbroking.in (DP related)
This content is for educational purpose only. Securities quoted are exemplary and not recommendatory.
Research Services are offered by Bajaj Broking as Research Analyst under SEBI Regn: INH000010043.
For more disclaimer, check here: https://www.bajajbroking.in/disclaimer